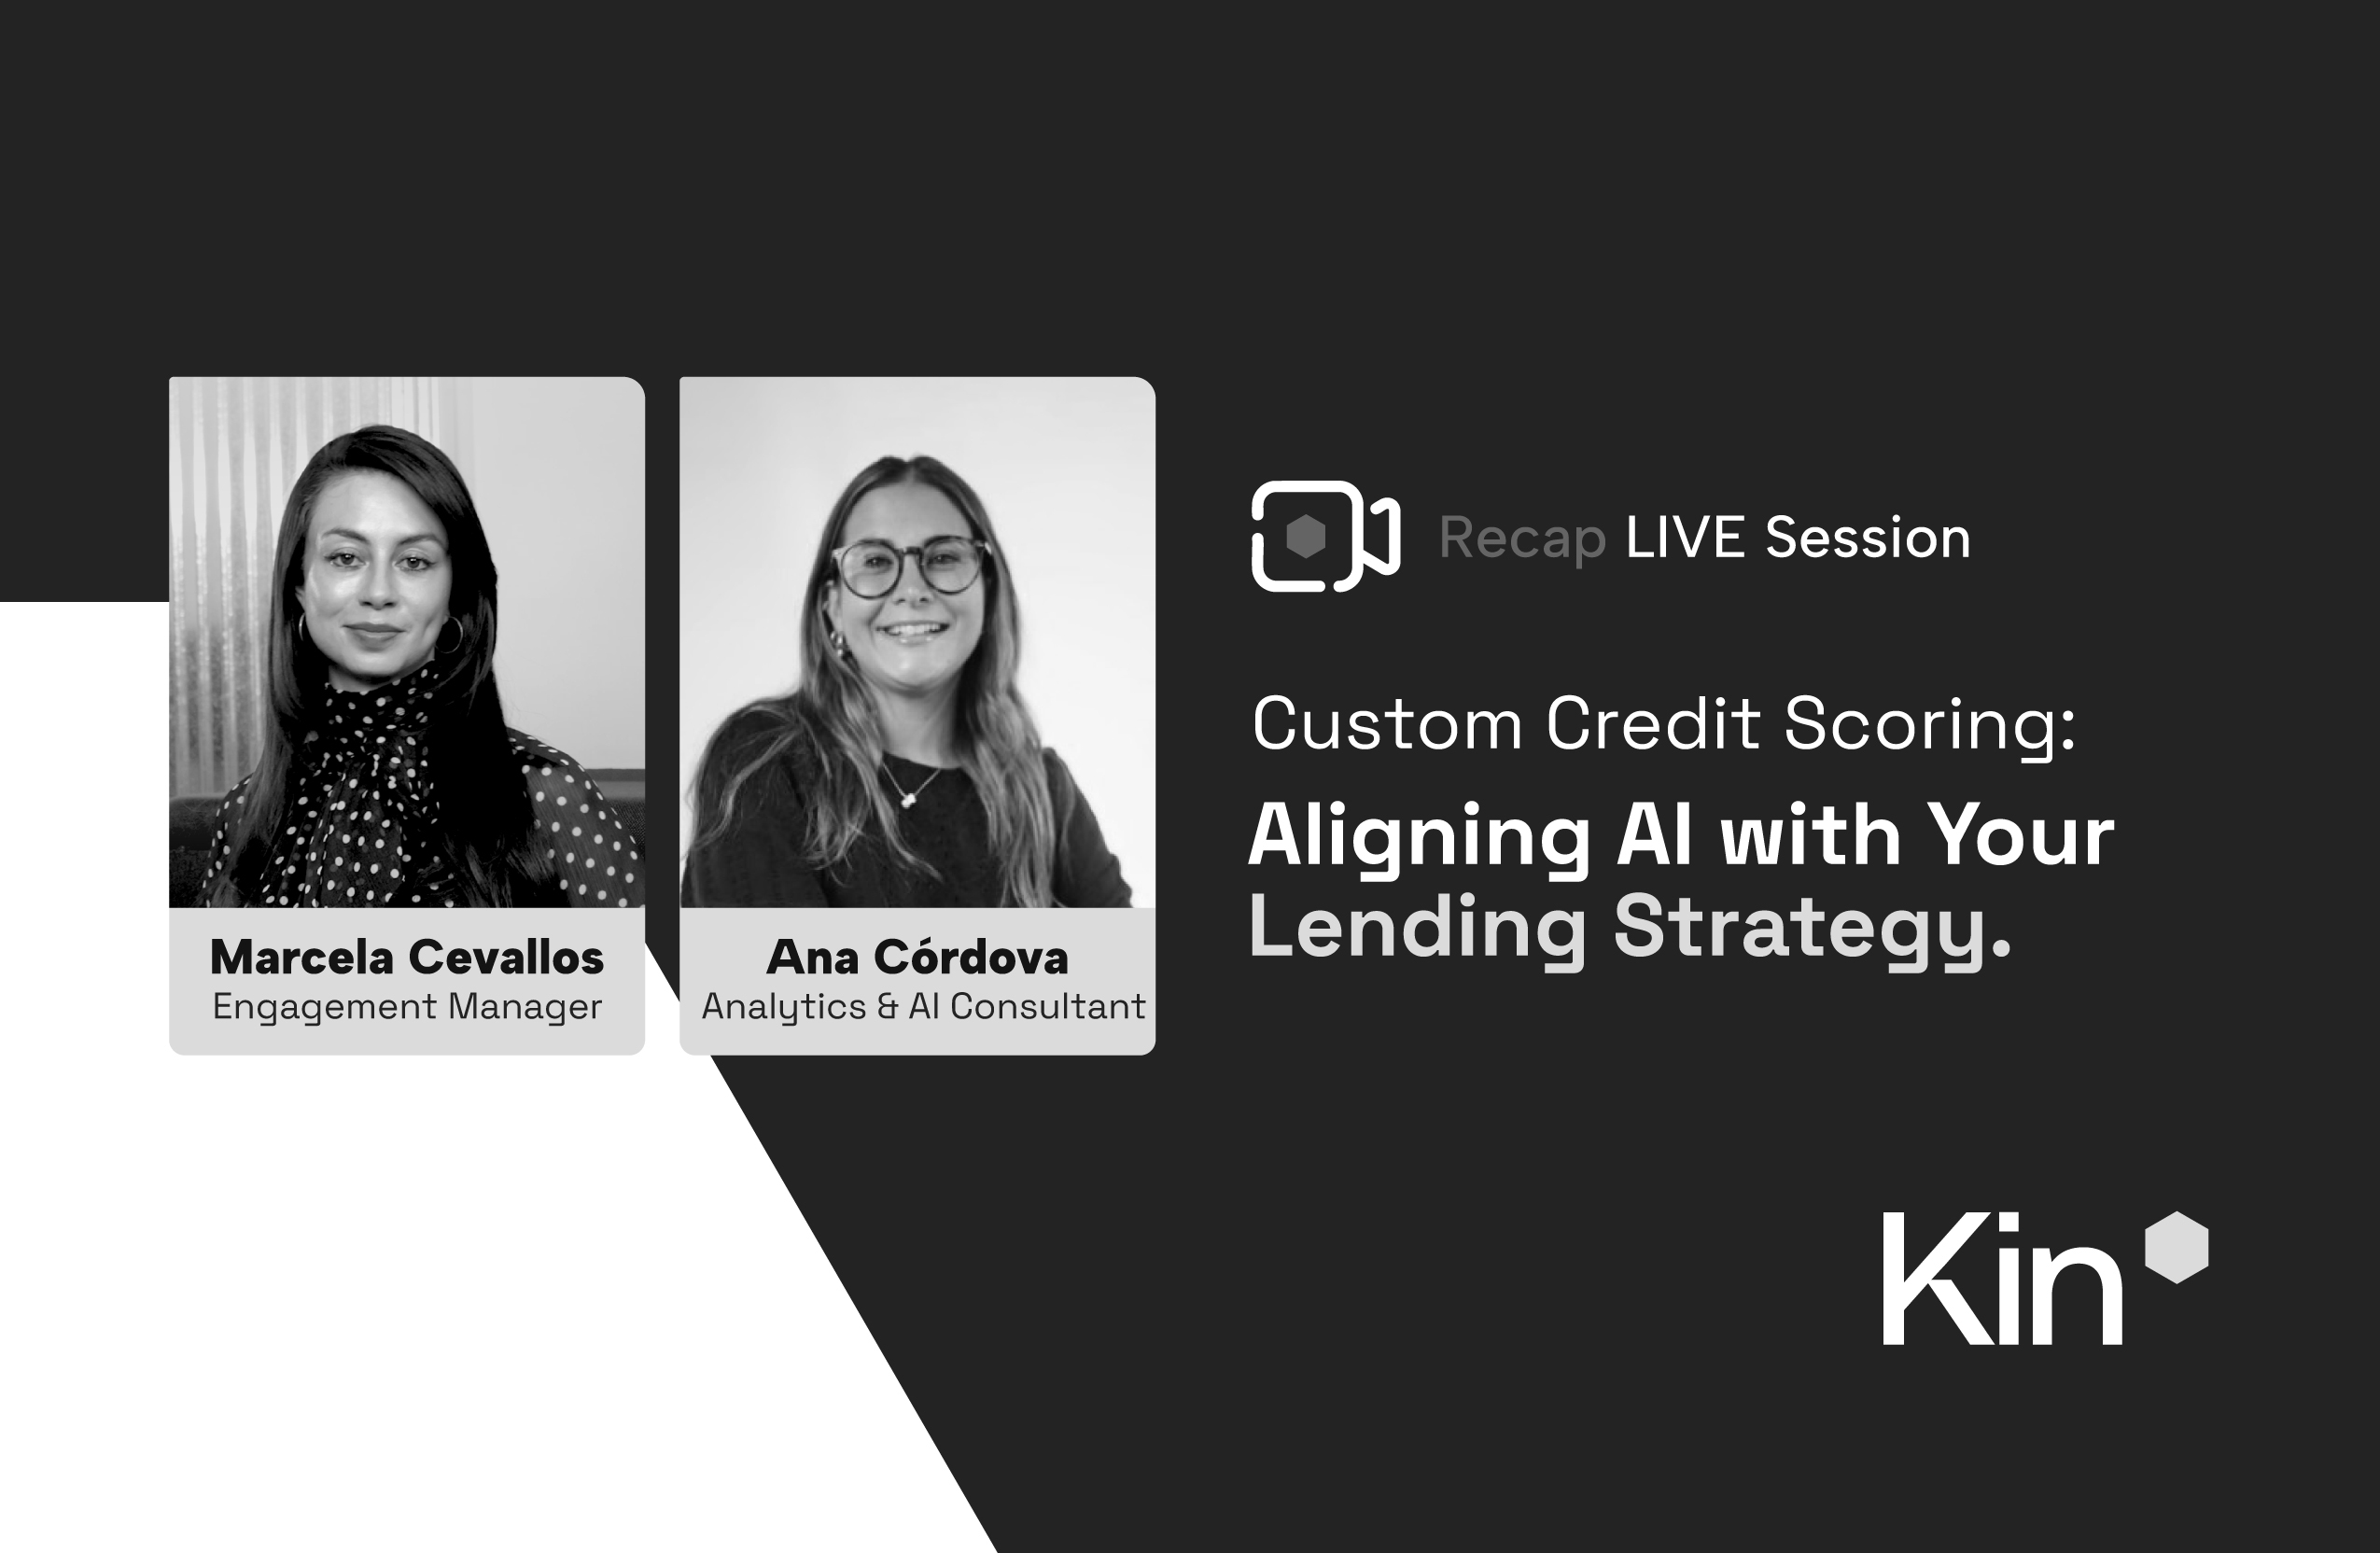
Webinar: Custom Credit Scoring: Aligning AI with your Lending Strategy
Most lenders already have a credit model. The harder question is whether that model still matches the portfolio it decides on. New verticals, a changed ticket mix and new broker relationships arrive faster than most scoring models get retrained, and the gap that opens is not a data problem. It is a decisioning problem.
This session walks through what it takes to align a credit model with the lending strategy it is meant to serve, and where generic scoring quietly stops working on an equipment finance book.
What the session covers
- Why off-the-shelf scoring underperforms on equipment finance portfolios, and the specific signals it cannot see
- How a model trained on a lender's own funded-deal history differs from one trained on industry averages
- What model decay looks like in practice, and how often retraining actually needs to happen
- Keeping every decision explainable and defensible as the model carries more of the work
- Where a custom model sits alongside bureau data rather than replacing it
Key takeaways
A model is only as current as the portfolio it learned from. A scoring model built two or three years ago was trained on a book that has since changed shape. It keeps producing confident answers about a portfolio it no longer recognises, which is more dangerous than producing none.
The signals are already in the lender's own data. In transportation and asset-based portfolios, the patterns that precede a default typically surface six to nine months before a missed payment. A generic model cannot see them, because it never trained on a book like that one.
Explainability is not a compliance tax. A plain-language rationale on every decision is what makes an adverse action defensible, and it is also what lets a credit team trust the score enough to act on it at volume.
Start with the decision, not the technology. Speeding up a flawed credit decision does not make it right. It just makes it wrong faster. Smarter first, then faster.
Frequently asked questions
How is a custom credit scoring model different from a bureau score?
A bureau score is anchored in industry averages across a very broad population. A custom model is trained on how deals in one specific portfolio have actually performed, so it reflects that lender's verticals, ticket sizes and risk appetite. The two work together: enriched bureau data feeds the custom model rather than competing with it.
How often does a credit model need retraining?
It depends on how fast the book is changing, but the trigger is portfolio drift rather than the calendar. When a lender enters a new vertical, shifts ticket mix or takes on new broker relationships, the model's training data stops describing the deals it is scoring.
Can a lender do this without fixing their data first?
Yes. Legacy portfolio data almost never arrives clean. Organising, mapping and structuring historical deal data is part of the engagement, not a prerequisite for starting one.
Related reading: Custom vs off-the-shelf credit scoring in equipment finance, 6 critical AI lifecycle stages in lending, and Risk Decisioning: custom credit scoring models.